Pennsylvania’s Educational Improvement Tax Credit
Pennsylvania’s Educational Improvement Tax Credit (EITC) program allows individuals and businesses to receive a state tax credit (not a deduction) equal to 90% of their Pennsylvania state tax liability for eligible contributions. These contributions must be directed to a non-profit organization registered with the program. Search Reading Symphony Orchestra registration at DCED.pa.gov >
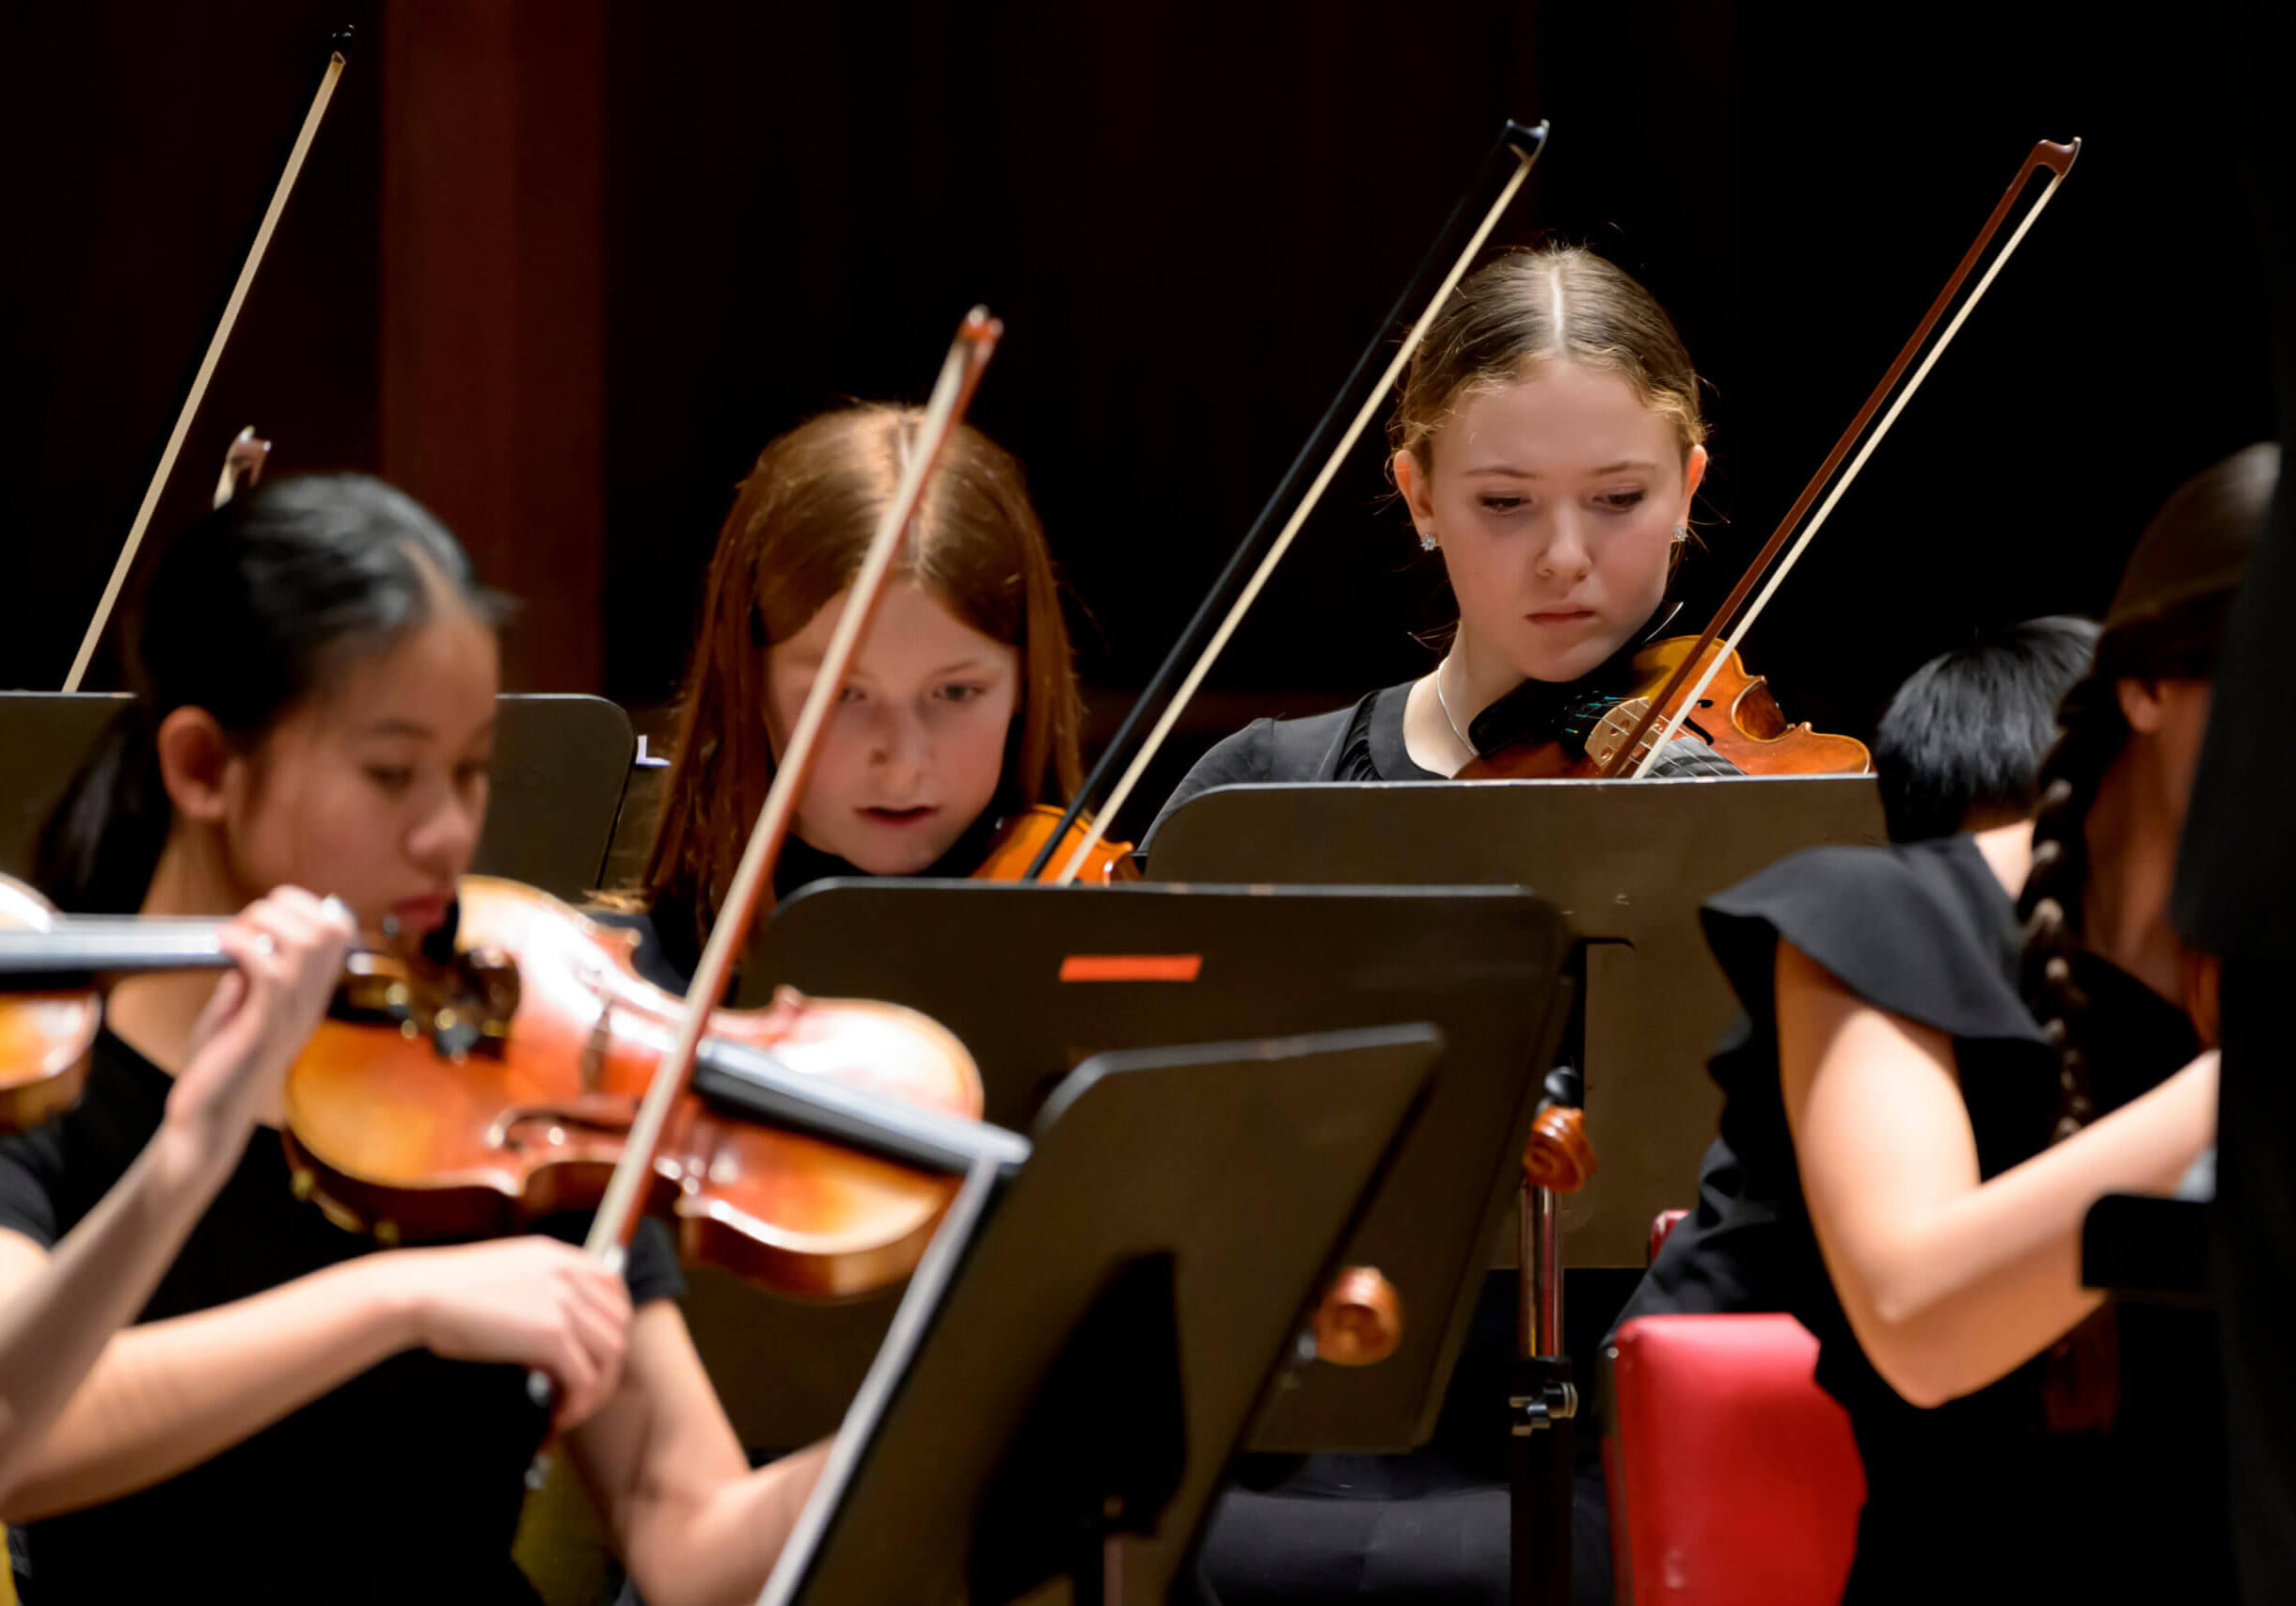
Youth Orchestras
The Reading Symphony Youth Orchestra and Reading Symphony Orchestra Junior Strings trains young musicians in large ensembles.
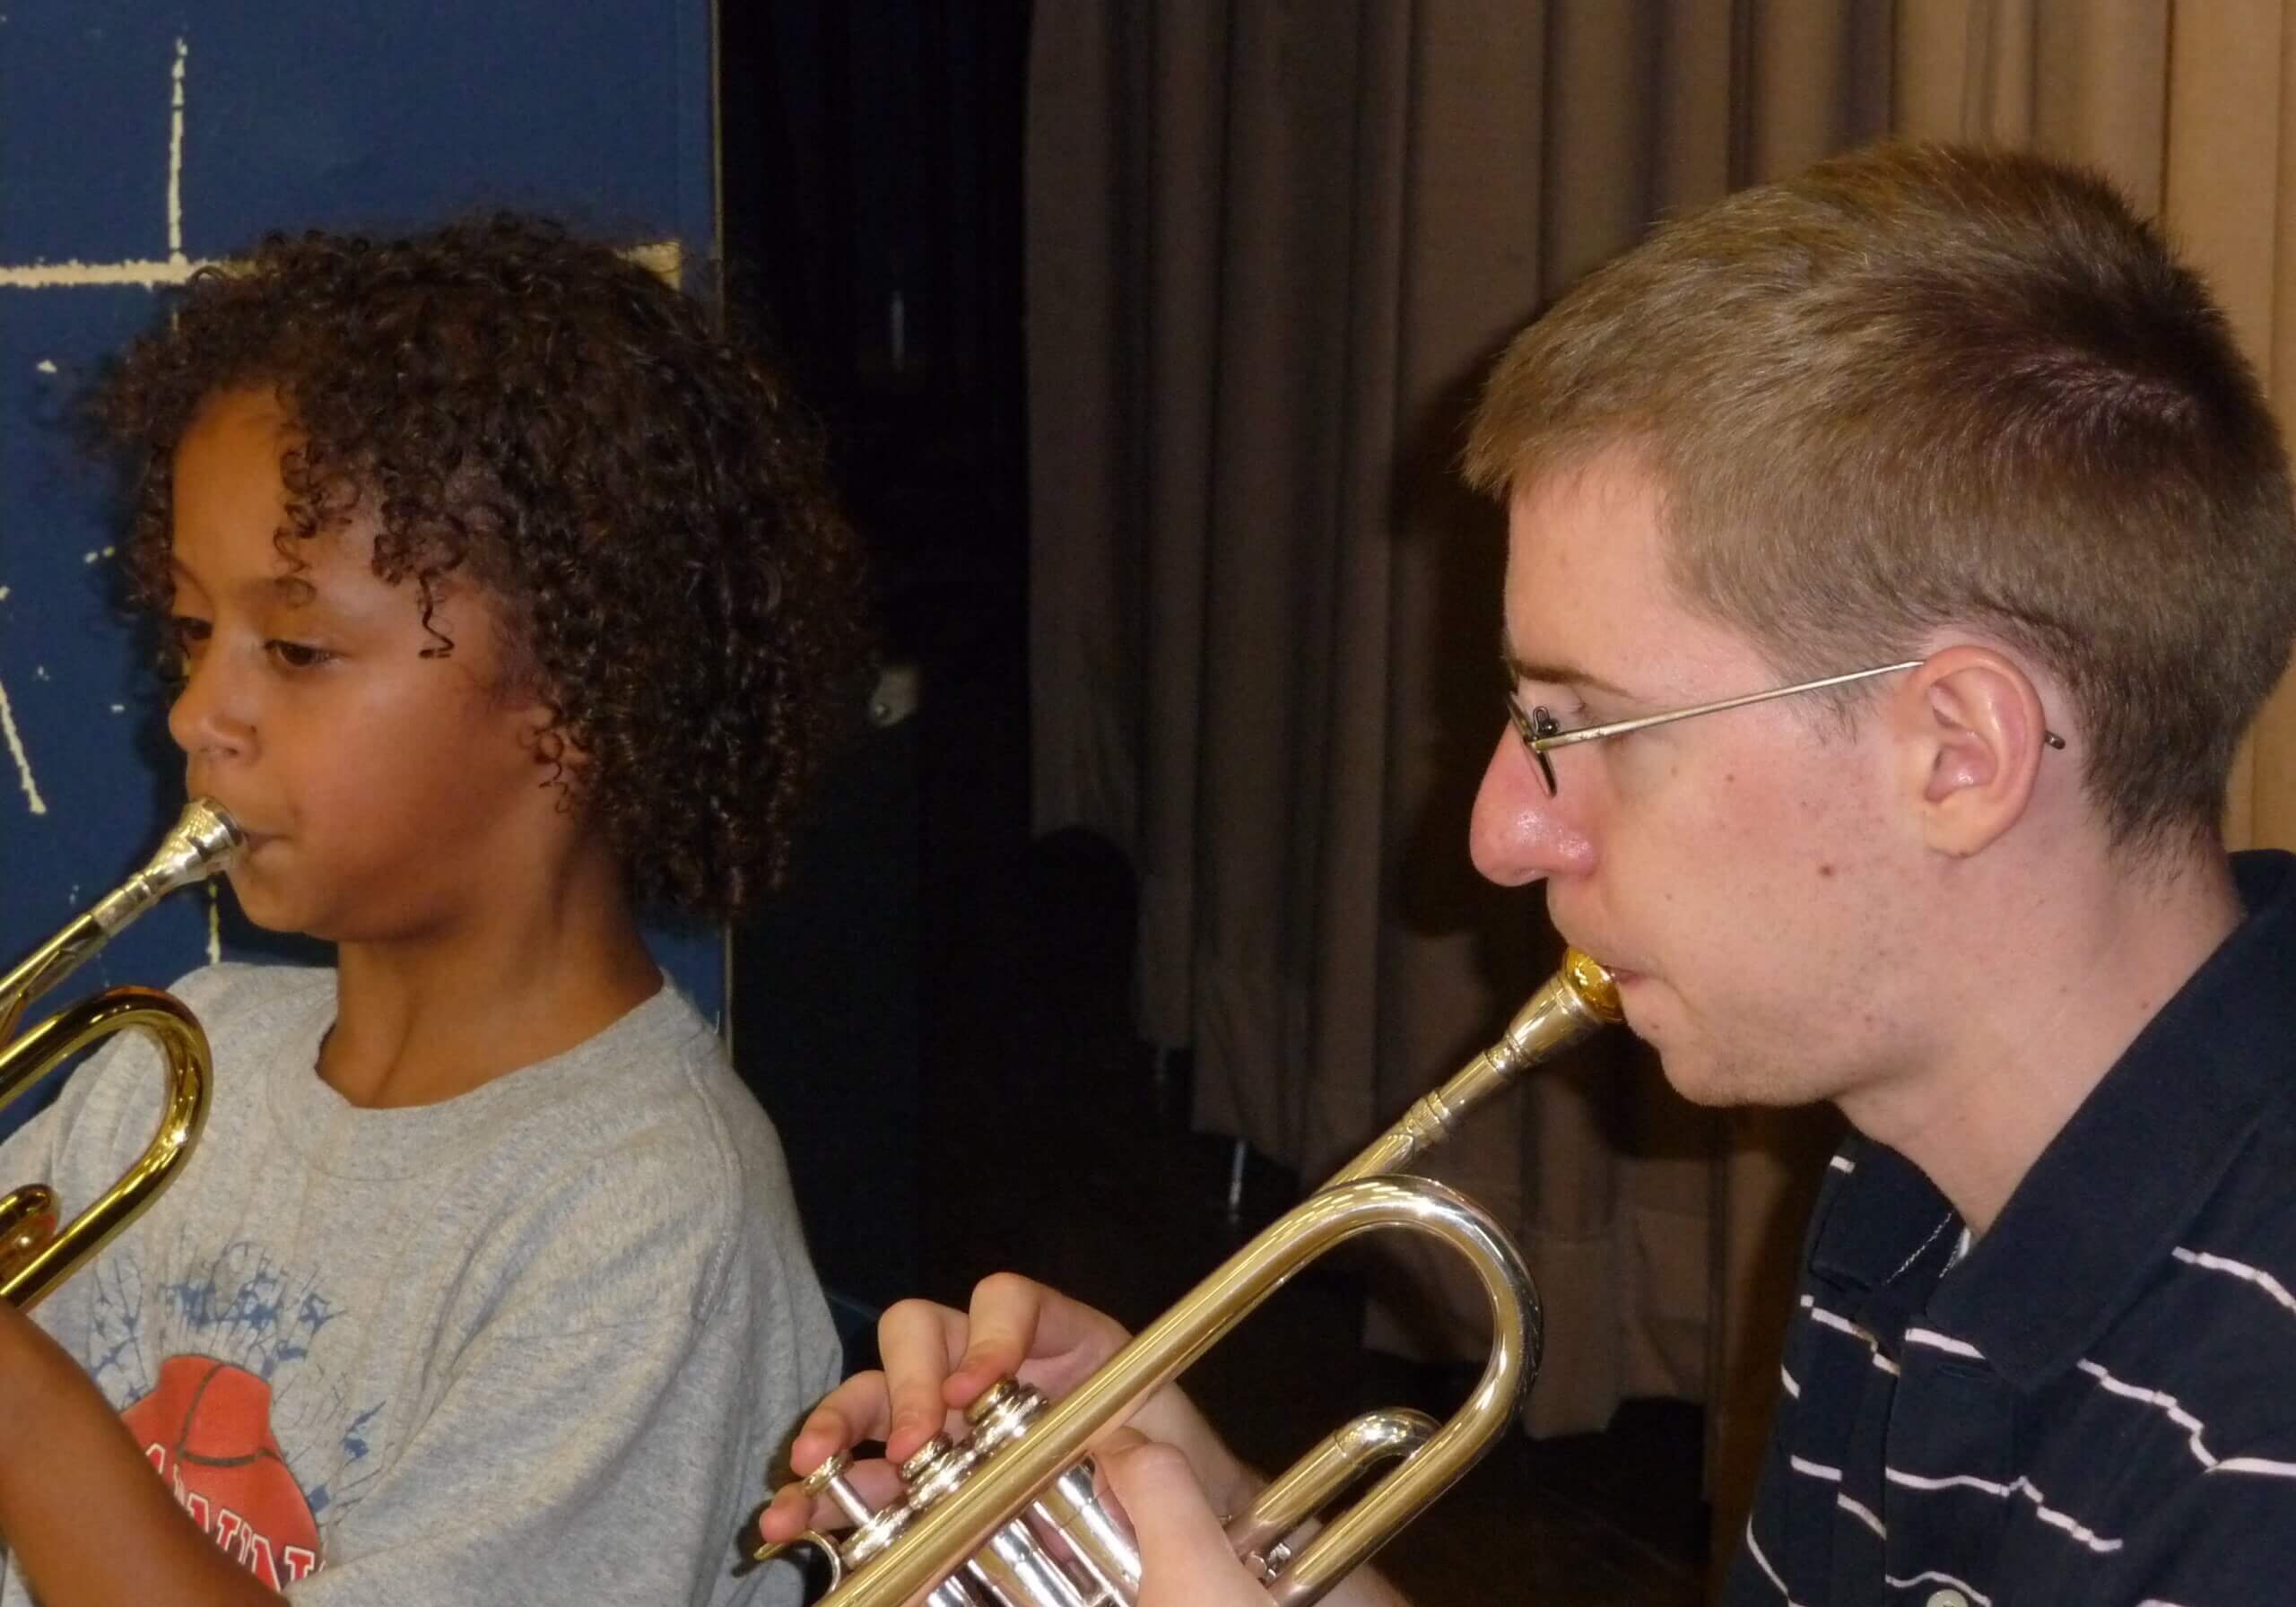
Orchestra Zone
Orchestra Zone is the RSO's flagship program offering free weekly private music lessons to students in the Reading School District.
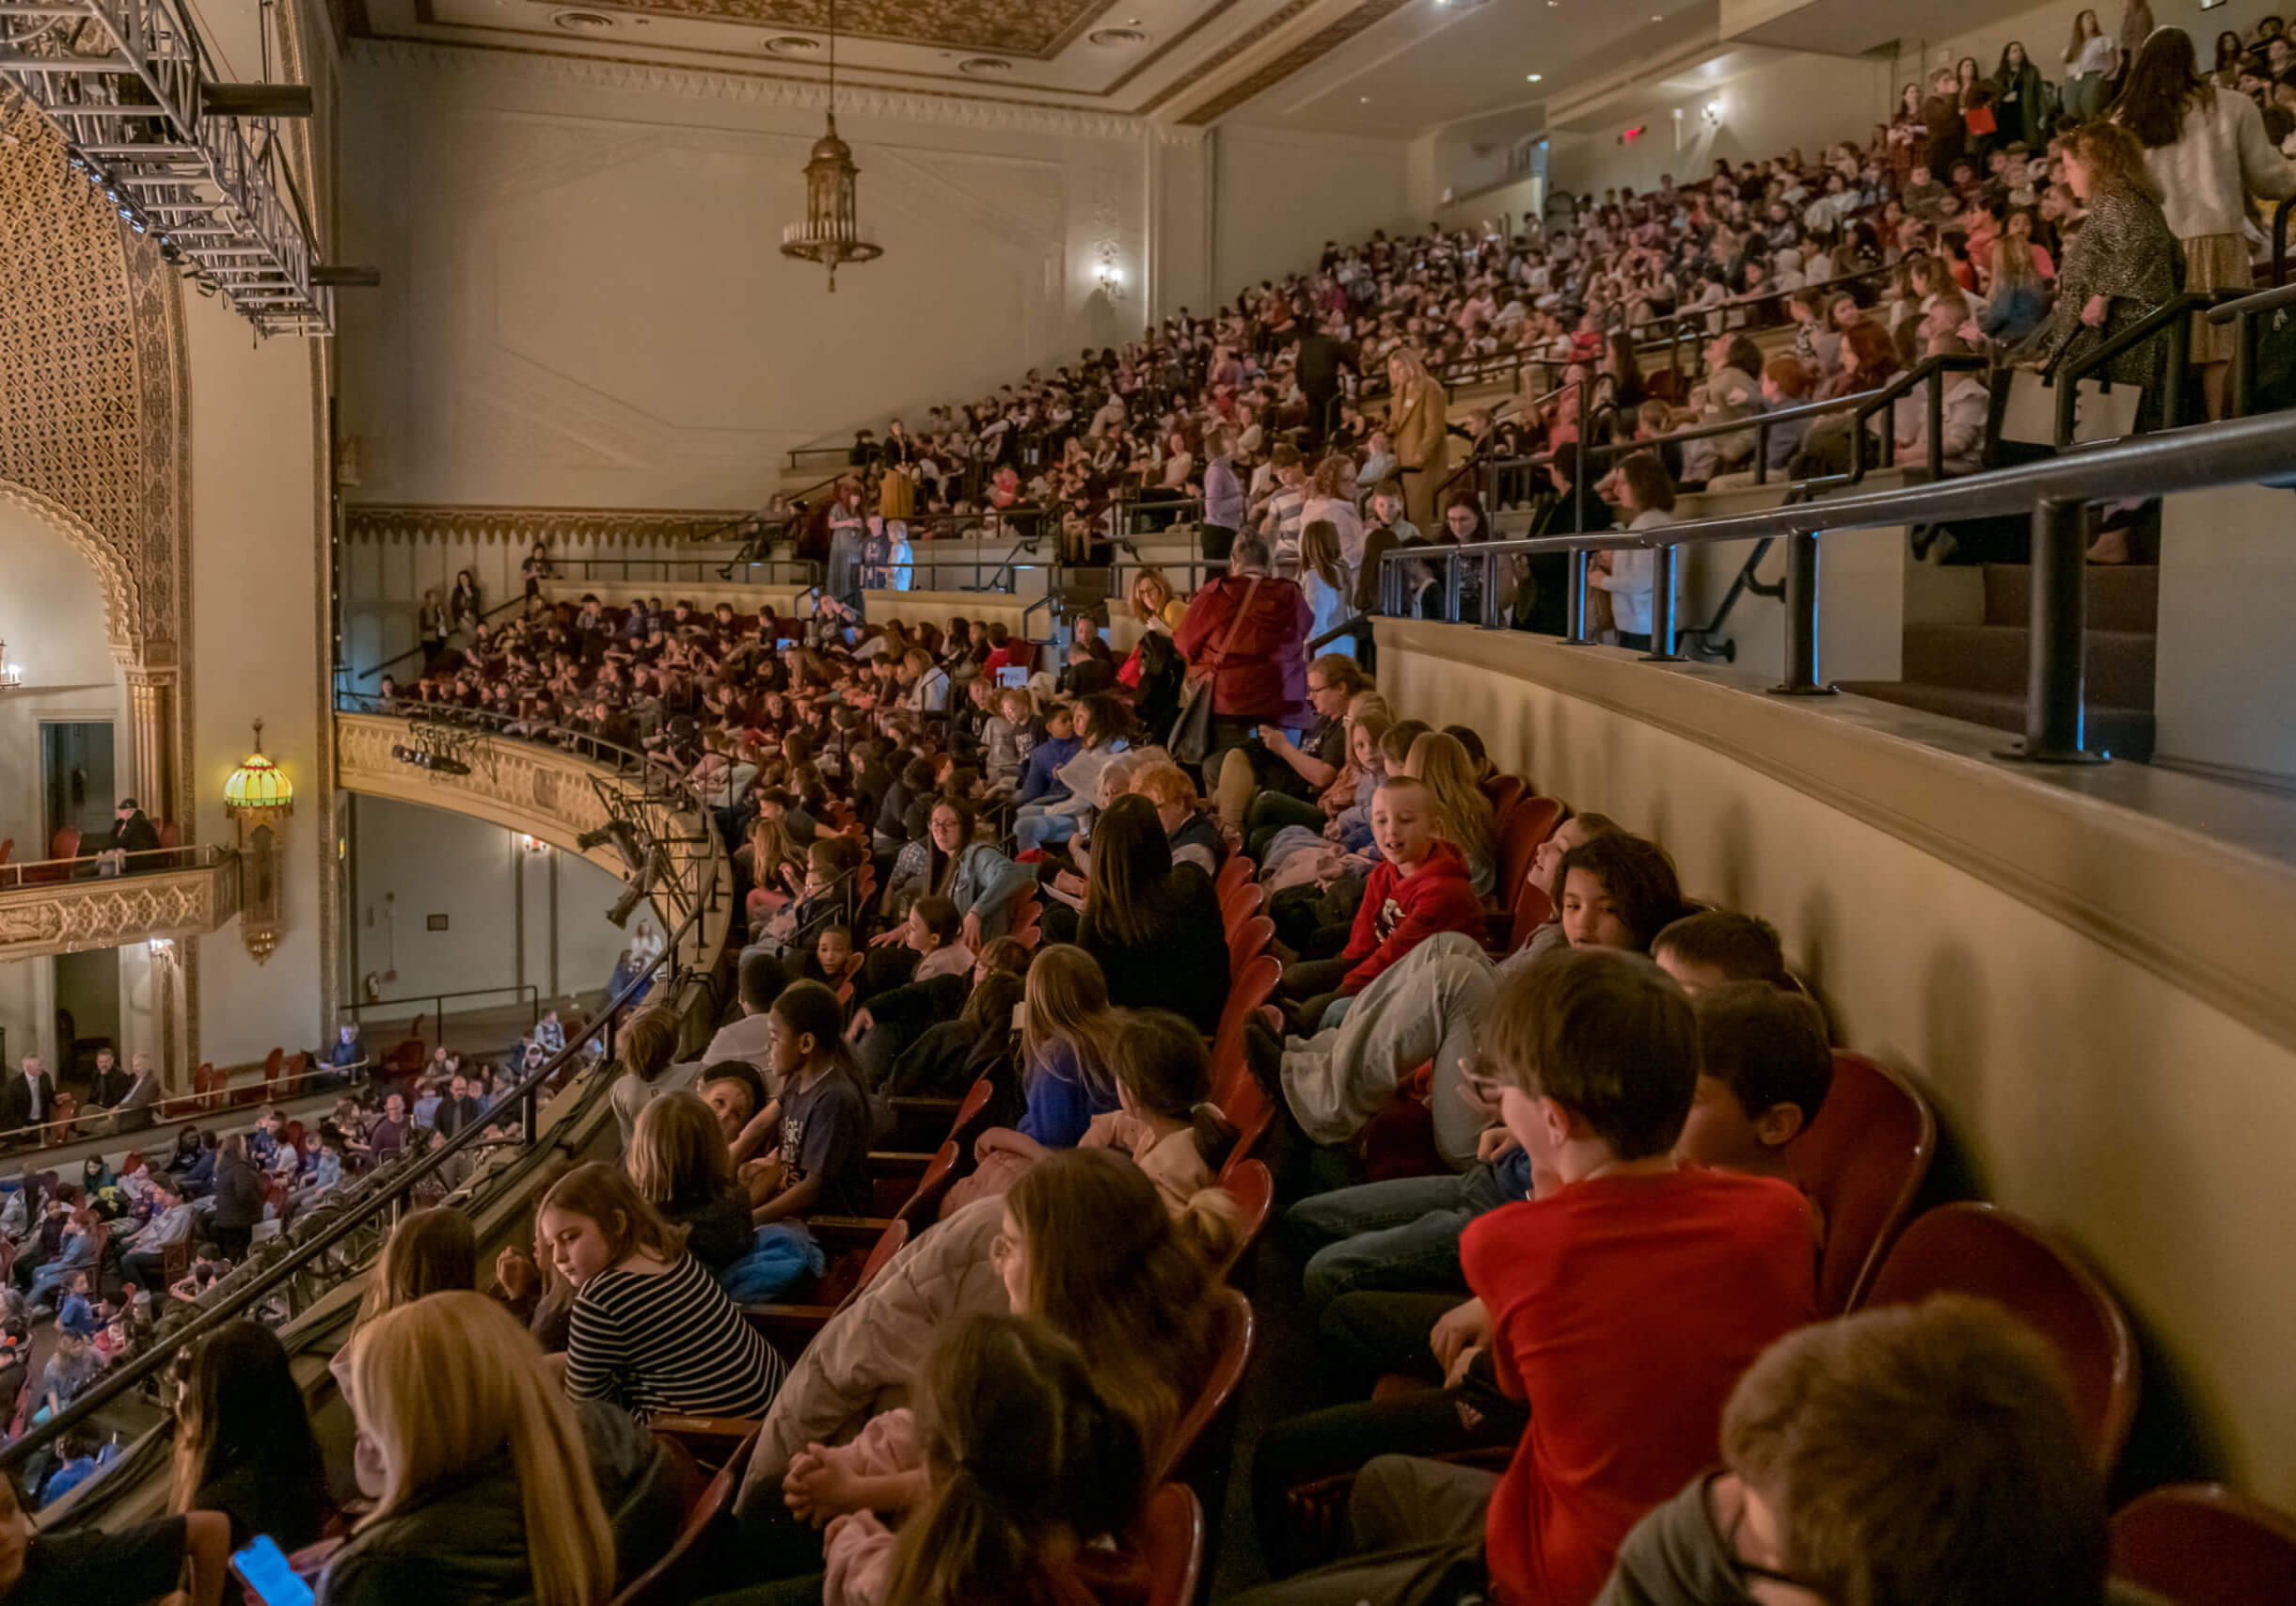
Student Concerts
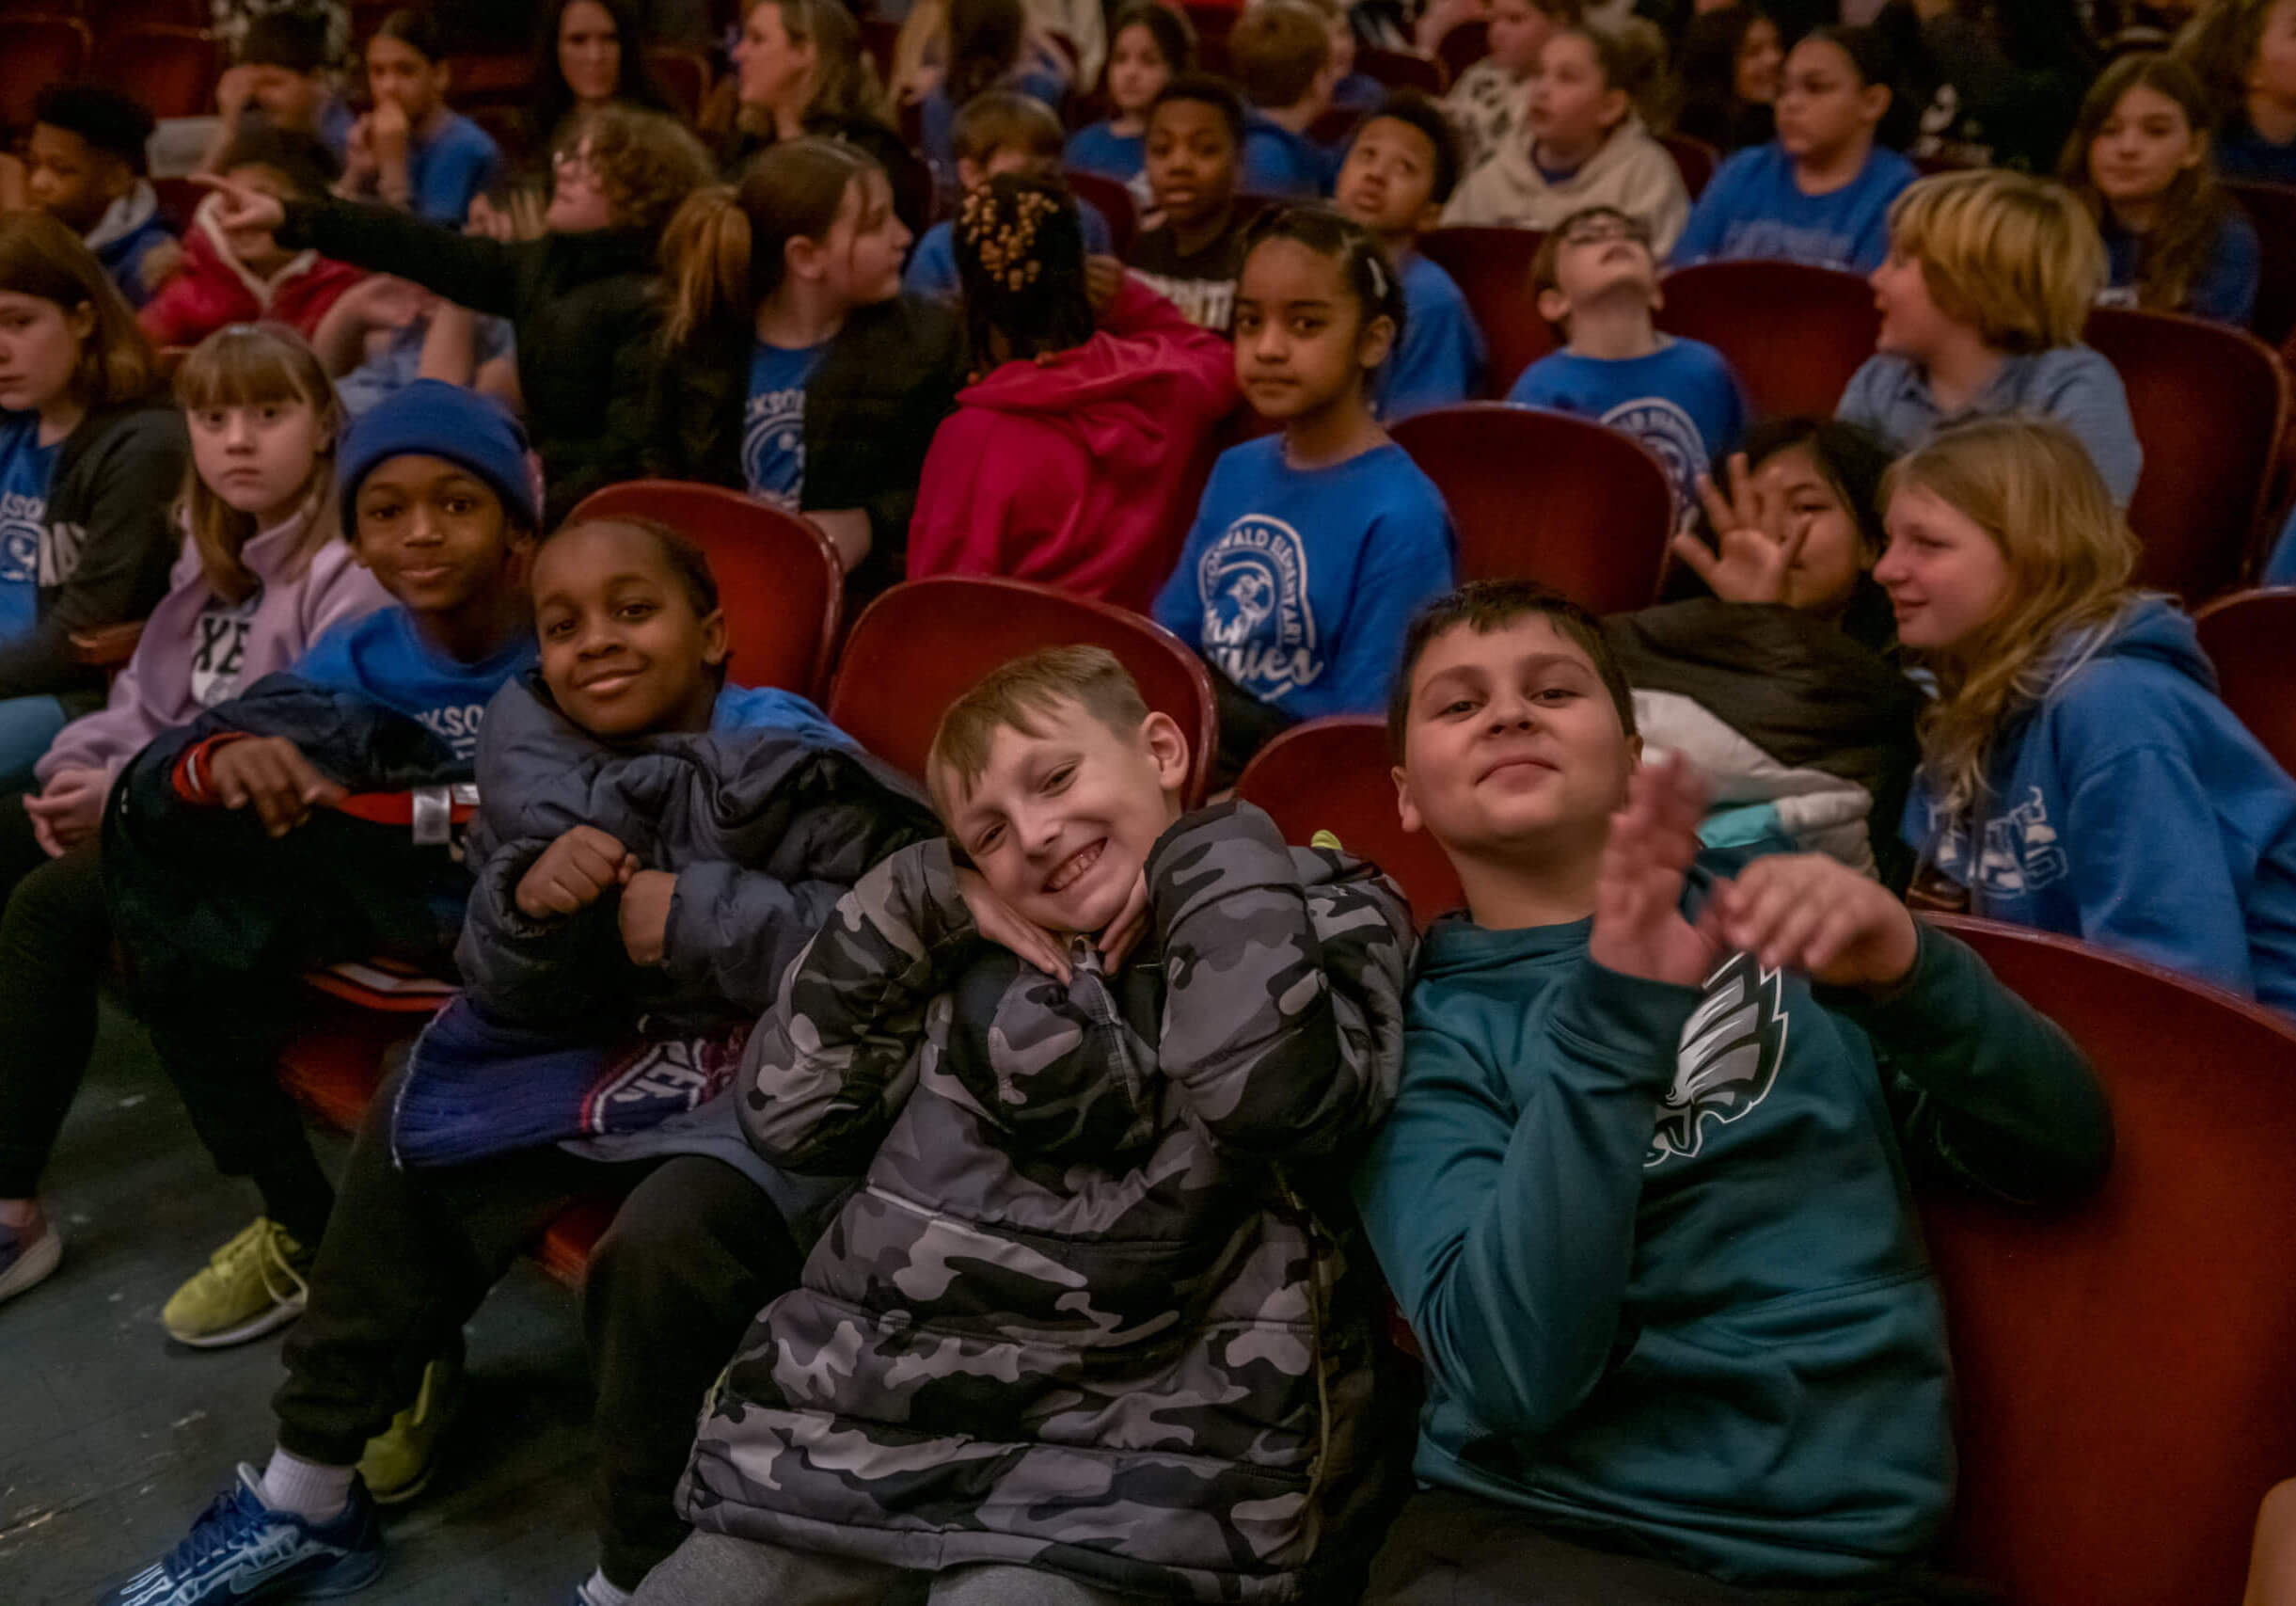
Each year the RSO reaches thousands of students through free student concerts offered to all schools in Berks county at the Santander Performing Arts Center
Put Your Tax Liabilty to Good Use
Through the establishment of Educational Improvement Tax Credit (EITC) and Opportunity Scholarship Tax Credit (OSTC) programs, donors can receive up to a 90% tax credit against their personal PA state tax liability by making their gift the RSO education programs.
What’s the difference between a credit and a deduction?
- Tax Credits directly reduce your tax liability on a dollar-for-dollar basis. For example, a $1,000 credit lowers your tax bill by $1,000.
- Tax Deductions, on the other hand, lower your taxable income based on your tax bracket. For example, if you are in the 35% tax bracket, a $1,000 deduction reduces your tax bill by $350.
- The EITC credit is equal to 90% of the donor’s contribution. Example: A $10,000 donation yields a $9,000 credit.
Does the PA EITC program offer a tax credit or a tax deduction?
Both. Donors receive:
- A 90% tax credit on their Pennsylvania state tax liability.
- A federal deduction for the remaining 10%. In some instances, business donors may obtain a 100% federal deduction if there is a reasonable expectation of a financial return commensurate with the amount donated.
Are individuals eligible to participate?
Individuals cannot participate directly, but may join a Special Purpose Entity (“SPE”) which distributes tax credits to individuals.
A SPE is a limited liability company that exists solely for the purpose of obtaining tax credits in the EITC program. Individuals sign a joinder agreement and make their contribution to the SPE. The SPE transfers 100% of the contribution to the RSO through the EITC program.
Pennsylvania’s Educational Improvement Tax Credit (“EITC”) program allows businesses to make contributions to certain 501(c)(3) organizations that offer enrichment programming to youths.
Funds donated to RSO though this program provide enrichment programming for students. In turn, participants receive a 90% tax credit, as well as, recognition in our widely disseminated BRAVO!, contributor features at events, listing the businesses on materials distributed, or other significant public recognition.
Because a business qualifies for both a federal deduction and a state income tax credit, donations will be cash flow positive in most circumstances. Below is an example of how the program works for a taxpayer who has a marginal federal rate of 37%.
| Costs | Benefits | |
| Payment to RSO through the EITC program | ($100,000) | |
| Deduction under I.R.C. § 162 (funds given to accredited 501(c)(3) organizations) |
$37,000 |
|
| Non-refundable PA state tax credit | $90,000 | |
| Total | ($100,000) | $127,000 |
| Net tax benefit | $27,000 | |
Your Taxes Support Your Choice
Individuals who pay Pennsylvania income taxes and businesses that are authorized to do business in Pennsylvania who are subject to one or more of the following taxes:
-
-
-
-
-
Personal Income Tax, Sub-chapter S-corporations and other “pass-through” entities will be able to use the credit against the shareholders’, members’, or partners’ PA personal income taxes
-
Corporate Net Income Tax
-
Malt Beverage Tax
-
Bank and Trust Company Shares Tax
-
Insurance Premiums Tax (excluding surplus lines, unauthorized, domestic/foreign marine)
-
Mutual Thrift Institutions Tax
-
Title Insurance Companies Shares Tax
-
Retaliatory Fees under Section 212 of the Insurance Company Law of 1921
-
-
-
-